

Frequently asked questions
Do you have a question? You're not alone! On our FAQ page, you’ll quickly and easily find answers to the most common questions about our products, services, and processes. Whether you want to know more about applying for a business loan, how we operate, or what to expect, you’ll find clear explanations here. Can’t find your question? Our team is happy to help. Feel free to contact us! We’re here for you every working day!
We always need a transaction summary of your business bank account. How to download such an overview is explained here. We may need additional information about your company to determine your financial position. For example, with relatively large requests. This includes VAT returns, information about the debtor and creditor position and the financial statements.
We only provide to companies that are registered with the Chamber of Commerce (KvK) in the Netherlands with a business bank account. In addition, you must be economically active for at least one year and have a turnover of at least €50,000 in the past year.
Swishfund is a recognized SME financier that has been supporting entrepreneurs in the Netherlands since 2016 with fast and accessible business financing, combining the efficiency of fintech technology with personalized service.
We look at this per situation. We think it is important that you can afford the loan. Swishfund provides loans ranging from €3,000 to €500,000. We can calculate your credit space without obligation and free of charge.
Once your application is completed and reviewed positively, we will deposit the money into your business account within 24 hours.
During the application, you can specify the desired amount, the term and purpose of the loan. In addition, we always ask you to upload a transaction summary of your business bank account in the MT940 file format. You can easily download such an overview from your bank's online environment. After we have calculated your credit space, we will contact you for the next steps. Depending on the size of the request, we need a number of additional documents.
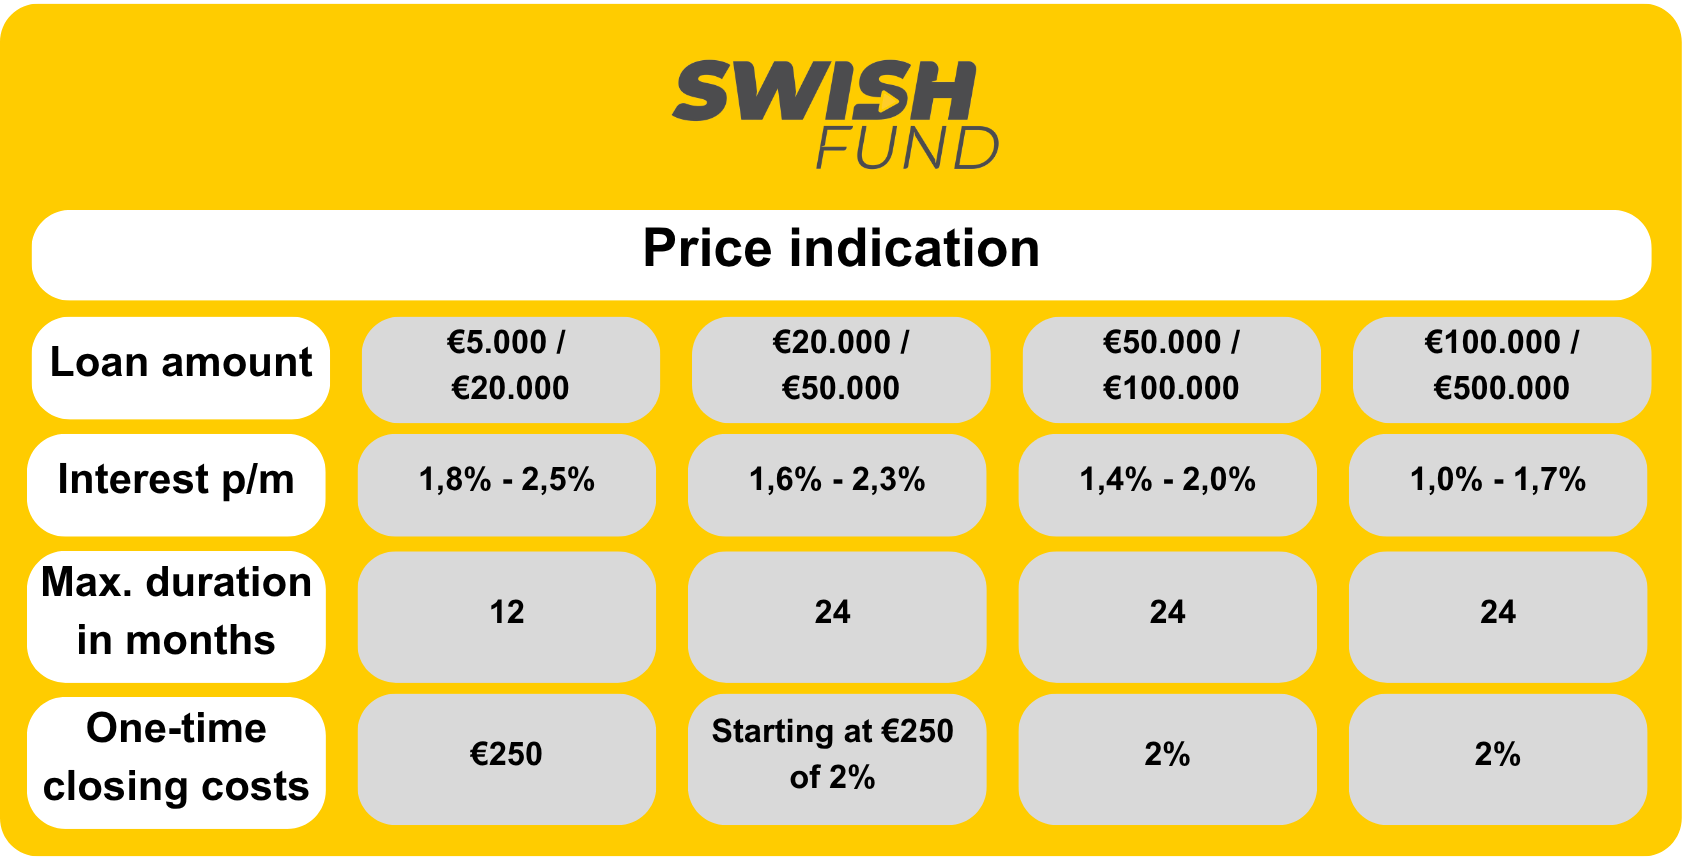
The cost of your loan consists of a one-off closing fee and a monthly interest. The amount of these costs is percentage and therefore depends on the loan amount. The standard closing fee is 2% with a minimum amount of €650. The monthly interest is determined based on your company's risk profile. You will receive a final proposal after reviewing your application. To give you a clear picture of the costs for business loans, we have drawn up two examples, showing the possible costs in a so-called UKO (Uniform Credit Overview). See examples here.
Under certain circumstances (in consultation with you, or unilaterally by us if you are in default) we may choose to extend the term of your loan. This is subject to the following conditions:
- You pay a new premium.
- You pay an extension fee of 5% of the outstanding amount, unless we agree otherwise.
The extension is recorded in an amended definitive payment schedule, which we will send you. We will then collect payments according to the new schedule.
Yes, definitely. If you do not have an ATM, we will provide a direct debit.
Yes, you can. You can always repay all or part of the loan earlier than at the end of the term. We do not charge a penalty, but you still have to pay the agreed interest. If you repay the loan completely earlier, we will give you an interest discount. The sooner you repay the loan in full, the higher the premium discount is.
According to the Golden Balance Sheet Rule, the maturity of the assets on the balance sheet must be very similar to the maturity of the assets on the same balance sheet. Roughly speaking, this means that fixed assets — assets held for more than one year — must be financed with long-term capital (= equity, provisions and long-term debt). The current assets, held for less than one year, can be financed with short-term debt.
The spending goal is the destination of your loan. In other words, what are you going to use the loan for? For example, pre-financing an order or purchasing inventory.
We can call on a guarantor if you fail to meet the payment agreement. We always ask you to vouch for the loan you take out yourself, or to have another (affiliated) person guarantee.
We may ask you to provide “securities”. This is also known as collateral. By pledging your securities, we get the right to collect them if you are unable to meet the payment obligation.
A right of pledge is a security right that can be established over goods (such as inventory, machinery, stock or other movable property), over bank accounts, over receivables (current and future claims), over work in progress, or over intellectual property rights. This right is granted by the owner (the pledgor) to a creditor (the pledgee), for example a bank or a financier, as security for a loan or other financial obligation.
We only provide to companies that are registered with the Chamber of Commerce (KvK) in the Netherlands with a business bank account. In addition, you must be economically active for at least one year and have a turnover of at least €50,000 in the past year.
You can only use the loan to finance your business activities.
Swishfund is a recognized SME financier that has been supporting entrepreneurs in the Netherlands since 2016 with fast and accessible business financing, combining the efficiency of fintech technology with personalized service.
We look at this per situation. We think it is important that you can afford the loan. Swishfund provides loans ranging from €3,000 to €500,000. We can calculate your credit space without obligation and free of charge.
Where banks have partly stopped financing small and medium-sized businesses, Swishfund continues. By using smart technology, we are able to simplify the complexity of traditional corporate finance.
Our loans range from 3 months to 24 months. You can specify the desired duration yourself during the application.
The application itself takes 5 minutes. After a working day, we will contact you by email or phone to discuss the first results. Based on this, we request some additional information and strive to have the money in the account within a week.
Once your application is completed and reviewed positively, we will deposit the money into your business account within 24 hours.
During the application, you can specify the desired amount, the term and purpose of the loan. In addition, we always ask you to upload a transaction summary of your business bank account in the MT940 file format. You can easily download such an overview from your bank's online environment. After we have calculated your credit space, we will contact you for the next steps. Depending on the size of the request, we need a number of additional documents.
The cost of your loan consists of a one-off closing fee and a monthly interest. The amount of these costs is percentage and therefore depends on the loan amount. The standard closing fee is 2% with a minimum amount of €650. The monthly interest is determined based on your company's risk profile. You will receive a final proposal after reviewing your application. To give you a clear picture of the costs for business loans, we have drawn up two examples, showing the possible costs in a so-called UKO (Uniform Credit Overview). See examples here.
Wat gebeurt er nadat je een volledige aanvraag hebt ingediend?
We begrijpen dat snelheid voor jou als ondernemer belangrijk is. Daarom zetten wij alles op alles om jou, indien mogelijk, nog dezelfde dag te voorzien in jouw financieringsbehoefte.
Na het indienen van je aanvraag doen we eerst een snelle analyse om te bepalen of je in aanmerking komt voor een financiering. Als dat er goed uitziet, nemen we contact met je op om de aanvraag samen verder te bespreken.
Afhankelijk van de omvang van de aanvraag kunnen we om een aantal extra documenten vragen.
Tot slot kijken onze analisten nogmaals zorgvuldig naar je situatie. We willen er zeker van zijn dat je het krediet kunt dragen en dat je een financiering ontvangt die past bij jouw bedrijf en persoonlijke situatie.
Als alles in orde is, ontvang je een digitaal contract van ons. Dit kun je eenvoudig online ondertekenen. Zodra we de ondertekende overeenkomst hebben ontvangen, maken we het bedrag meestal nog dezelfde dag over naar je zakelijke rekening. Zo heb je snel beschikking over het geld om te investeren in jouw onderneming.
We always need a transaction summary of your business bank account. How to download such an overview is explained here. We may need additional information about your company to determine your financial position. For example, with relatively large requests. This includes VAT returns, information about the debtor and creditor position and the financial statements.
We only provide to companies that are registered with the Chamber of Commerce (KvK) in the Netherlands with a business bank account. In addition, you must be economically active for at least one year and have a turnover of at least €50,000 in the past year.
We look at this per situation. We think it is important that you can afford the loan. Swishfund provides loans ranging from €3,000 to €500,000. We can calculate your credit space without obligation and free of charge.
The application itself takes 5 minutes. After a working day, we will contact you by email or phone to discuss the first results. Based on this, we request some additional information and strive to have the money in the account within a week.
Once your application is completed and reviewed positively, we will deposit the money into your business account within 24 hours.
During the application, you can specify the desired amount, the term and purpose of the loan. In addition, we always ask you to upload a transaction summary of your business bank account in the MT940 file format. You can easily download such an overview from your bank's online environment. After we have calculated your credit space, we will contact you for the next steps. Depending on the size of the request, we need a number of additional documents.
The cost of your loan consists of a one-off closing fee and a monthly interest. The amount of these costs is percentage and therefore depends on the loan amount. The standard closing fee is 2% with a minimum amount of €650. The monthly interest is determined based on your company's risk profile. You will receive a final proposal after reviewing your application. To give you a clear picture of the costs for business loans, we have drawn up two examples, showing the possible costs in a so-called UKO (Uniform Credit Overview). See examples here.
For repayment, we usually use automatic direct debit, tailored to your business cash flow. If your business has a card payment terminal through which most of your income comes in (such as in hospitality or retail, for example), card revenue skimming via CCV, PinDirect or MultiSafePay is also an option. In that case, you repay a fixed percentage of your card turnover. On busy days you pay more, on quiet days less.
After 25% of your term, you can repay your business loan penalty-free.
You are in default if you:
- Allow a direct debit to fail, resulting in a payment arrears.
- Fail to comply with other contractual obligations.
In the event of default:
- You may receive a notice of default, giving you a reasonable period to meet your obligations.
- We may, if the situation is not resolved, demand immediate repayment of the loan.
If we claim the entire loan earlier, you must immediately repay us the entire loan and pay any other amounts that we are entitled to under your agreement with us.
- You owe us penalty interest on any amount you pay us late, for the period from the date you were due to pay until the day you pay. The penalty interest is the same as the statutory commercial interest rate.
- Upon first request, you must reimburse us for all costs we incur in connection with or under the applicable claim ground. Contrary to the Cash Income Expenses Act, the extrajudicial collection costs are 15% of the total amount due.
- We can make use of all the securities. In that case, you may not ask the preliminary relief judge for a different way of selling.
- We may ask you for extra guarantees. You must then ensure that those securities are established immediately.
It is essential for us that our collections to your bank account go smoothly. You are therefore not allowed to close or change your bank account, nor make changes to your collection authorization, unless we have indicated by letter or email that we agree.
If a collection fails, you are in default and we may do anything the law allows us to do and/or one or more of the following:
- Reclaim as many times as necessary to make up for the failed collection.
- Adjust the frequency of collections
- Incorporate the failed collection into your final payment schedule. We will continue collecting based on the adjusted final payment schedule.
- Extend the term of your loan.
Make sure your bank account(s) and direct debit authorisation remain unchanged. Changes are only permitted with our explicit consent.
In the loan agreement, we indicate, for informational purposes, the amount you must repay and in how many instalments. Repayments generally take place on a daily basis. After we have paid out the loan to you, we will provide you with a definitive repayment schedule.
Yes, definitely. If you do not have an ATM, we will provide a direct debit.
Yes, you can. You can always repay all or part of the loan earlier than at the end of the term. We do not charge a penalty, but you still have to pay the agreed interest. If you repay the loan completely earlier, we will give you an interest discount. The sooner you repay the loan in full, the higher the premium discount is.
This depends on the company's risk profile in combination with the size of the application. We provide loans with an interest starting at 1% per month.
According to the Golden Balance Sheet Rule, the maturity of the assets on the balance sheet must be very similar to the maturity of the assets on the same balance sheet. Roughly speaking, this means that fixed assets — assets held for more than one year — must be financed with long-term capital (= equity, provisions and long-term debt). The current assets, held for less than one year, can be financed with short-term debt.
In the loan agreement, we indicate, for informational purposes, the amount you must repay and in how many instalments. Repayments generally take place on a daily basis. After we have paid out the loan to you, we will provide you with a definitive repayment schedule.
This depends on the company's risk profile in combination with the size of the application. We provide loans with an interest starting at 1% per month.
The cost of your loan consists of a one-off closing fee and a monthly interest. The amount of these costs is percentage and therefore depends on the loan amount. The standard closing fee is 2% with a minimum amount of €650. The monthly interest is determined based on your company's risk profile. You will receive a final proposal after reviewing your application. To give you a clear picture of the costs for business loans, we have drawn up two examples, showing the possible costs in a so-called UKO (Uniform Credit Overview). See examples here.
We can call on a guarantor if you fail to meet the payment agreement. We always ask you to vouch for the loan you take out yourself, or to have another (affiliated) person guarantee.
We may ask you to provide “securities”. This is also known as collateral. By pledging your securities, we get the right to collect them if you are unable to meet the payment obligation.
We always need a transaction summary of your business bank account. How to download such an overview is explained here. We may need additional information about your company to determine your financial position. For example, with relatively large requests. This includes VAT returns, information about the debtor and creditor position and the financial statements.
A right of pledge is a security right that can be established over goods (such as inventory, machinery, stock or other movable property), over bank accounts, over receivables (current and future claims), over work in progress, or over intellectual property rights. This right is granted by the owner (the pledgor) to a creditor (the pledgee), for example a bank or a financier, as security for a loan or other financial obligation.
We only provide to companies that are registered with the Chamber of Commerce (KvK) in the Netherlands with a business bank account. In addition, you must be economically active for at least one year and have a turnover of at least €50,000 in the past year.
Wat gebeurt er nadat je een volledige aanvraag hebt ingediend?
We begrijpen dat snelheid voor jou als ondernemer belangrijk is. Daarom zetten wij alles op alles om jou, indien mogelijk, nog dezelfde dag te voorzien in jouw financieringsbehoefte.
Na het indienen van je aanvraag doen we eerst een snelle analyse om te bepalen of je in aanmerking komt voor een financiering. Als dat er goed uitziet, nemen we contact met je op om de aanvraag samen verder te bespreken.
Afhankelijk van de omvang van de aanvraag kunnen we om een aantal extra documenten vragen.
Tot slot kijken onze analisten nogmaals zorgvuldig naar je situatie. We willen er zeker van zijn dat je het krediet kunt dragen en dat je een financiering ontvangt die past bij jouw bedrijf en persoonlijke situatie.
Als alles in orde is, ontvang je een digitaal contract van ons. Dit kun je eenvoudig online ondertekenen. Zodra we de ondertekende overeenkomst hebben ontvangen, maken we het bedrag meestal nog dezelfde dag over naar je zakelijke rekening. Zo heb je snel beschikking over het geld om te investeren in jouw onderneming.
For repayment, we usually use automatic direct debit, tailored to your business cash flow. If your business has a card payment terminal through which most of your income comes in (such as in hospitality or retail, for example), card revenue skimming via CCV, PinDirect or MultiSafePay is also an option. In that case, you repay a fixed percentage of your card turnover. On busy days you pay more, on quiet days less.
After 25% of your term, you can repay your business loan penalty-free.
Under certain circumstances (in consultation with you, or unilaterally by us if you are in default) we may choose to extend the term of your loan. This is subject to the following conditions:
- You pay a new premium.
- You pay an extension fee of 5% of the outstanding amount, unless we agree otherwise.
The extension is recorded in an amended definitive payment schedule, which we will send you. We will then collect payments according to the new schedule.
You are in default if you:
- Allow a direct debit to fail, resulting in a payment arrears.
- Fail to comply with other contractual obligations.
In the event of default:
- You may receive a notice of default, giving you a reasonable period to meet your obligations.
- We may, if the situation is not resolved, demand immediate repayment of the loan.
If we claim the entire loan earlier, you must immediately repay us the entire loan and pay any other amounts that we are entitled to under your agreement with us.
- You owe us penalty interest on any amount you pay us late, for the period from the date you were due to pay until the day you pay. The penalty interest is the same as the statutory commercial interest rate.
- Upon first request, you must reimburse us for all costs we incur in connection with or under the applicable claim ground. Contrary to the Cash Income Expenses Act, the extrajudicial collection costs are 15% of the total amount due.
- We can make use of all the securities. In that case, you may not ask the preliminary relief judge for a different way of selling.
- We may ask you for extra guarantees. You must then ensure that those securities are established immediately.
It is essential for us that our collections to your bank account go smoothly. You are therefore not allowed to close or change your bank account, nor make changes to your collection authorization, unless we have indicated by letter or email that we agree.
If a collection fails, you are in default and we may do anything the law allows us to do and/or one or more of the following:
- Reclaim as many times as necessary to make up for the failed collection.
- Adjust the frequency of collections
- Incorporate the failed collection into your final payment schedule. We will continue collecting based on the adjusted final payment schedule.
- Extend the term of your loan.
Make sure your bank account(s) and direct debit authorisation remain unchanged. Changes are only permitted with our explicit consent.
In the loan agreement, we indicate, for informational purposes, the amount you must repay and in how many instalments. Repayments generally take place on a daily basis. After we have paid out the loan to you, we will provide you with a definitive repayment schedule.
Yes, definitely. If you do not have an ATM, we will provide a direct debit.
Yes, you can. You can always repay all or part of the loan earlier than at the end of the term. We do not charge a penalty, but you still have to pay the agreed interest. If you repay the loan completely earlier, we will give you an interest discount. The sooner you repay the loan in full, the higher the premium discount is.
This depends on the company's risk profile in combination with the size of the application. We provide loans with an interest starting at 1% per month.
According to the Golden Balance Sheet Rule, the maturity of the assets on the balance sheet must be very similar to the maturity of the assets on the same balance sheet. Roughly speaking, this means that fixed assets — assets held for more than one year — must be financed with long-term capital (= equity, provisions and long-term debt). The current assets, held for less than one year, can be financed with short-term debt.
The spending goal is the destination of your loan. In other words, what are you going to use the loan for? For example, pre-financing an order or purchasing inventory.
We can call on a guarantor if you fail to meet the payment agreement. We always ask you to vouch for the loan you take out yourself, or to have another (affiliated) person guarantee.
We may ask you to provide “securities”. This is also known as collateral. By pledging your securities, we get the right to collect them if you are unable to meet the payment obligation.
We always need a transaction summary of your business bank account. How to download such an overview is explained here. We may need additional information about your company to determine your financial position. For example, with relatively large requests. This includes VAT returns, information about the debtor and creditor position and the financial statements.
A right of pledge is a security right that can be established over goods (such as inventory, machinery, stock or other movable property), over bank accounts, over receivables (current and future claims), over work in progress, or over intellectual property rights. This right is granted by the owner (the pledgor) to a creditor (the pledgee), for example a bank or a financier, as security for a loan or other financial obligation.
We only provide to companies that are registered with the Chamber of Commerce (KvK) in the Netherlands with a business bank account. In addition, you must be economically active for at least one year and have a turnover of at least €50,000 in the past year.
You can only use the loan to finance your business activities.
Swishfund is a recognized SME financier that has been supporting entrepreneurs in the Netherlands since 2016 with fast and accessible business financing, combining the efficiency of fintech technology with personalized service.
We look at this per situation. We think it is important that you can afford the loan. Swishfund provides loans ranging from €3,000 to €500,000. We can calculate your credit space without obligation and free of charge.
Where banks have partly stopped financing small and medium-sized businesses, Swishfund continues. By using smart technology, we are able to simplify the complexity of traditional corporate finance.
Our loans range from 3 months to 24 months. You can specify the desired duration yourself during the application.
The application itself takes 5 minutes. After a working day, we will contact you by email or phone to discuss the first results. Based on this, we request some additional information and strive to have the money in the account within a week.
Once your application is completed and reviewed positively, we will deposit the money into your business account within 24 hours.
During the application, you can specify the desired amount, the term and purpose of the loan. In addition, we always ask you to upload a transaction summary of your business bank account in the MT940 file format. You can easily download such an overview from your bank's online environment. After we have calculated your credit space, we will contact you for the next steps. Depending on the size of the request, we need a number of additional documents.
The cost of your loan consists of a one-off closing fee and a monthly interest. The amount of these costs is percentage and therefore depends on the loan amount. The standard closing fee is 2% with a minimum amount of €650. The monthly interest is determined based on your company's risk profile. You will receive a final proposal after reviewing your application. To give you a clear picture of the costs for business loans, we have drawn up two examples, showing the possible costs in a so-called UKO (Uniform Credit Overview). See examples here.
We are here for you!
Our expert team is happy to assist you with applying for your business loan, answering questions about the costs of your business credit, or anything else you need. Feel free to get in touch with us. We’re available on working days from 9:00 AM to 5:30 PM.
1059CM Amsterdam
BTW NL856397805B01
Need help?

Swishfund is affiliated with the KiFiD
Can't we find a solution to the complaint together? Then you can contact the Financial Services Complaints Institute (KiFiD). Swishfund will always comply with the binding advice in the event of disputes.
To qualify for treatment via the Kifid, you will first have to go through Swishfund's internal complaints procedure. You do this by filing a complaint above.